<img height="1" width="1" style="display:none" src="https://www.facebook.com/tr?id=356276288176327&amp;ev=PageView&amp;noscript=1">
Skip to content

Dental Practice Transition Advisors

Selling a Dental Practice in Indiana

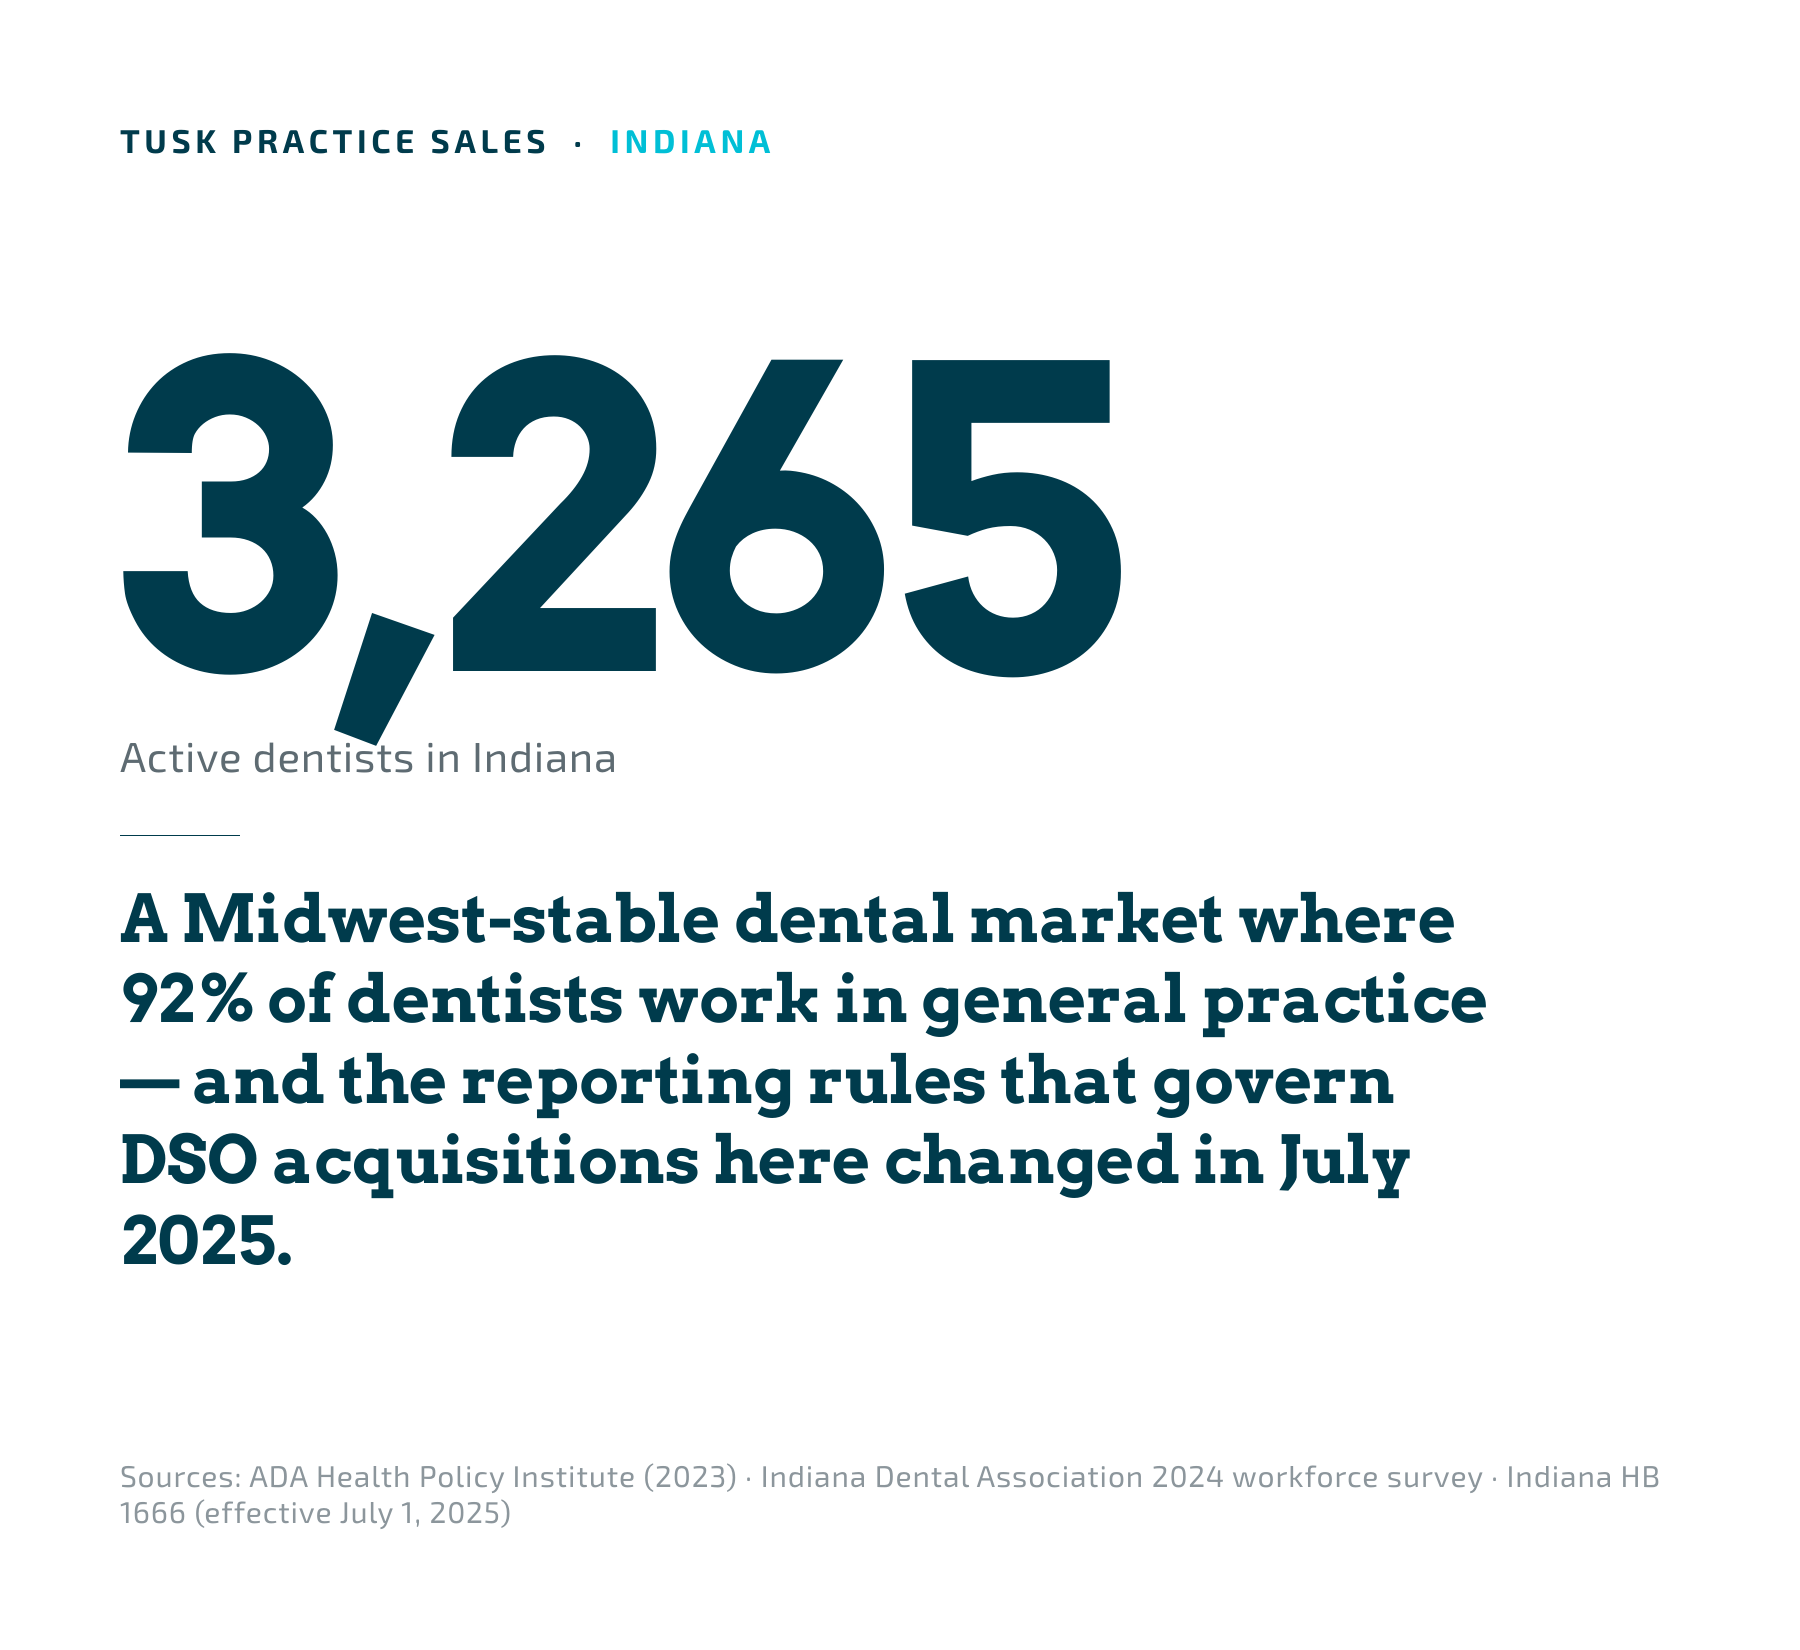
 TUSK is a sell-side M&A advisor for Indiana dental practice owners. Indiana's practice-ownership rule and the new HB 1666 reporting law change how DSO acquisitions have to be structured and disclosed here — and it changes what a competitive process can clear. 

Request a Confidential Valuation

What is your Indiana dental practice worth?

 A confidential valuation, prepared by our team. No commitment. We respond within two business days. 

Indiana Deals Are Structured Around a Rule Most Owners Don't Realize Applies to Them.

Indiana prohibits the corporate practice of dentistry — a doctrine that traces back to a 1939 state court decision and remains in force today. In practice: a DSO cannot own your practice directly. Every acquisition is structured through a management services arrangement with a dentist-owner retaining licensed ownership. That mechanism changes your tax treatment on close, the calibration of any earn-out, and the disclosure obligations both sides face. 

As of July 1, 2025, Indiana HB 1666 also revised the reporting requirements around DSO transactions — narrowing the definition of "health care entity" and altering which deals require prior notification. The deals structured cleanly under the new rules move faster and disclose less; the ones structured poorly get noticed. Knowing the difference before you go to market is the leverage. 

Start with a Valuation
Indiana dental market overview — 3,265 active dentists and the new HB 1666 reporting law

Indiana Dental Practice Sales - Closed.

Indiana dental practice owners are selling to some of the most active DSO and PE-backed buyers in the country. These are the groups competing for practices like yours.

Frame_3
Frame_2
Frame_1

Why Indiana Owners Don't Sell Without Sell-Side Counsel.

The Buyers Active in Indiana Are Not the Buyers Active in Sunbelt States.
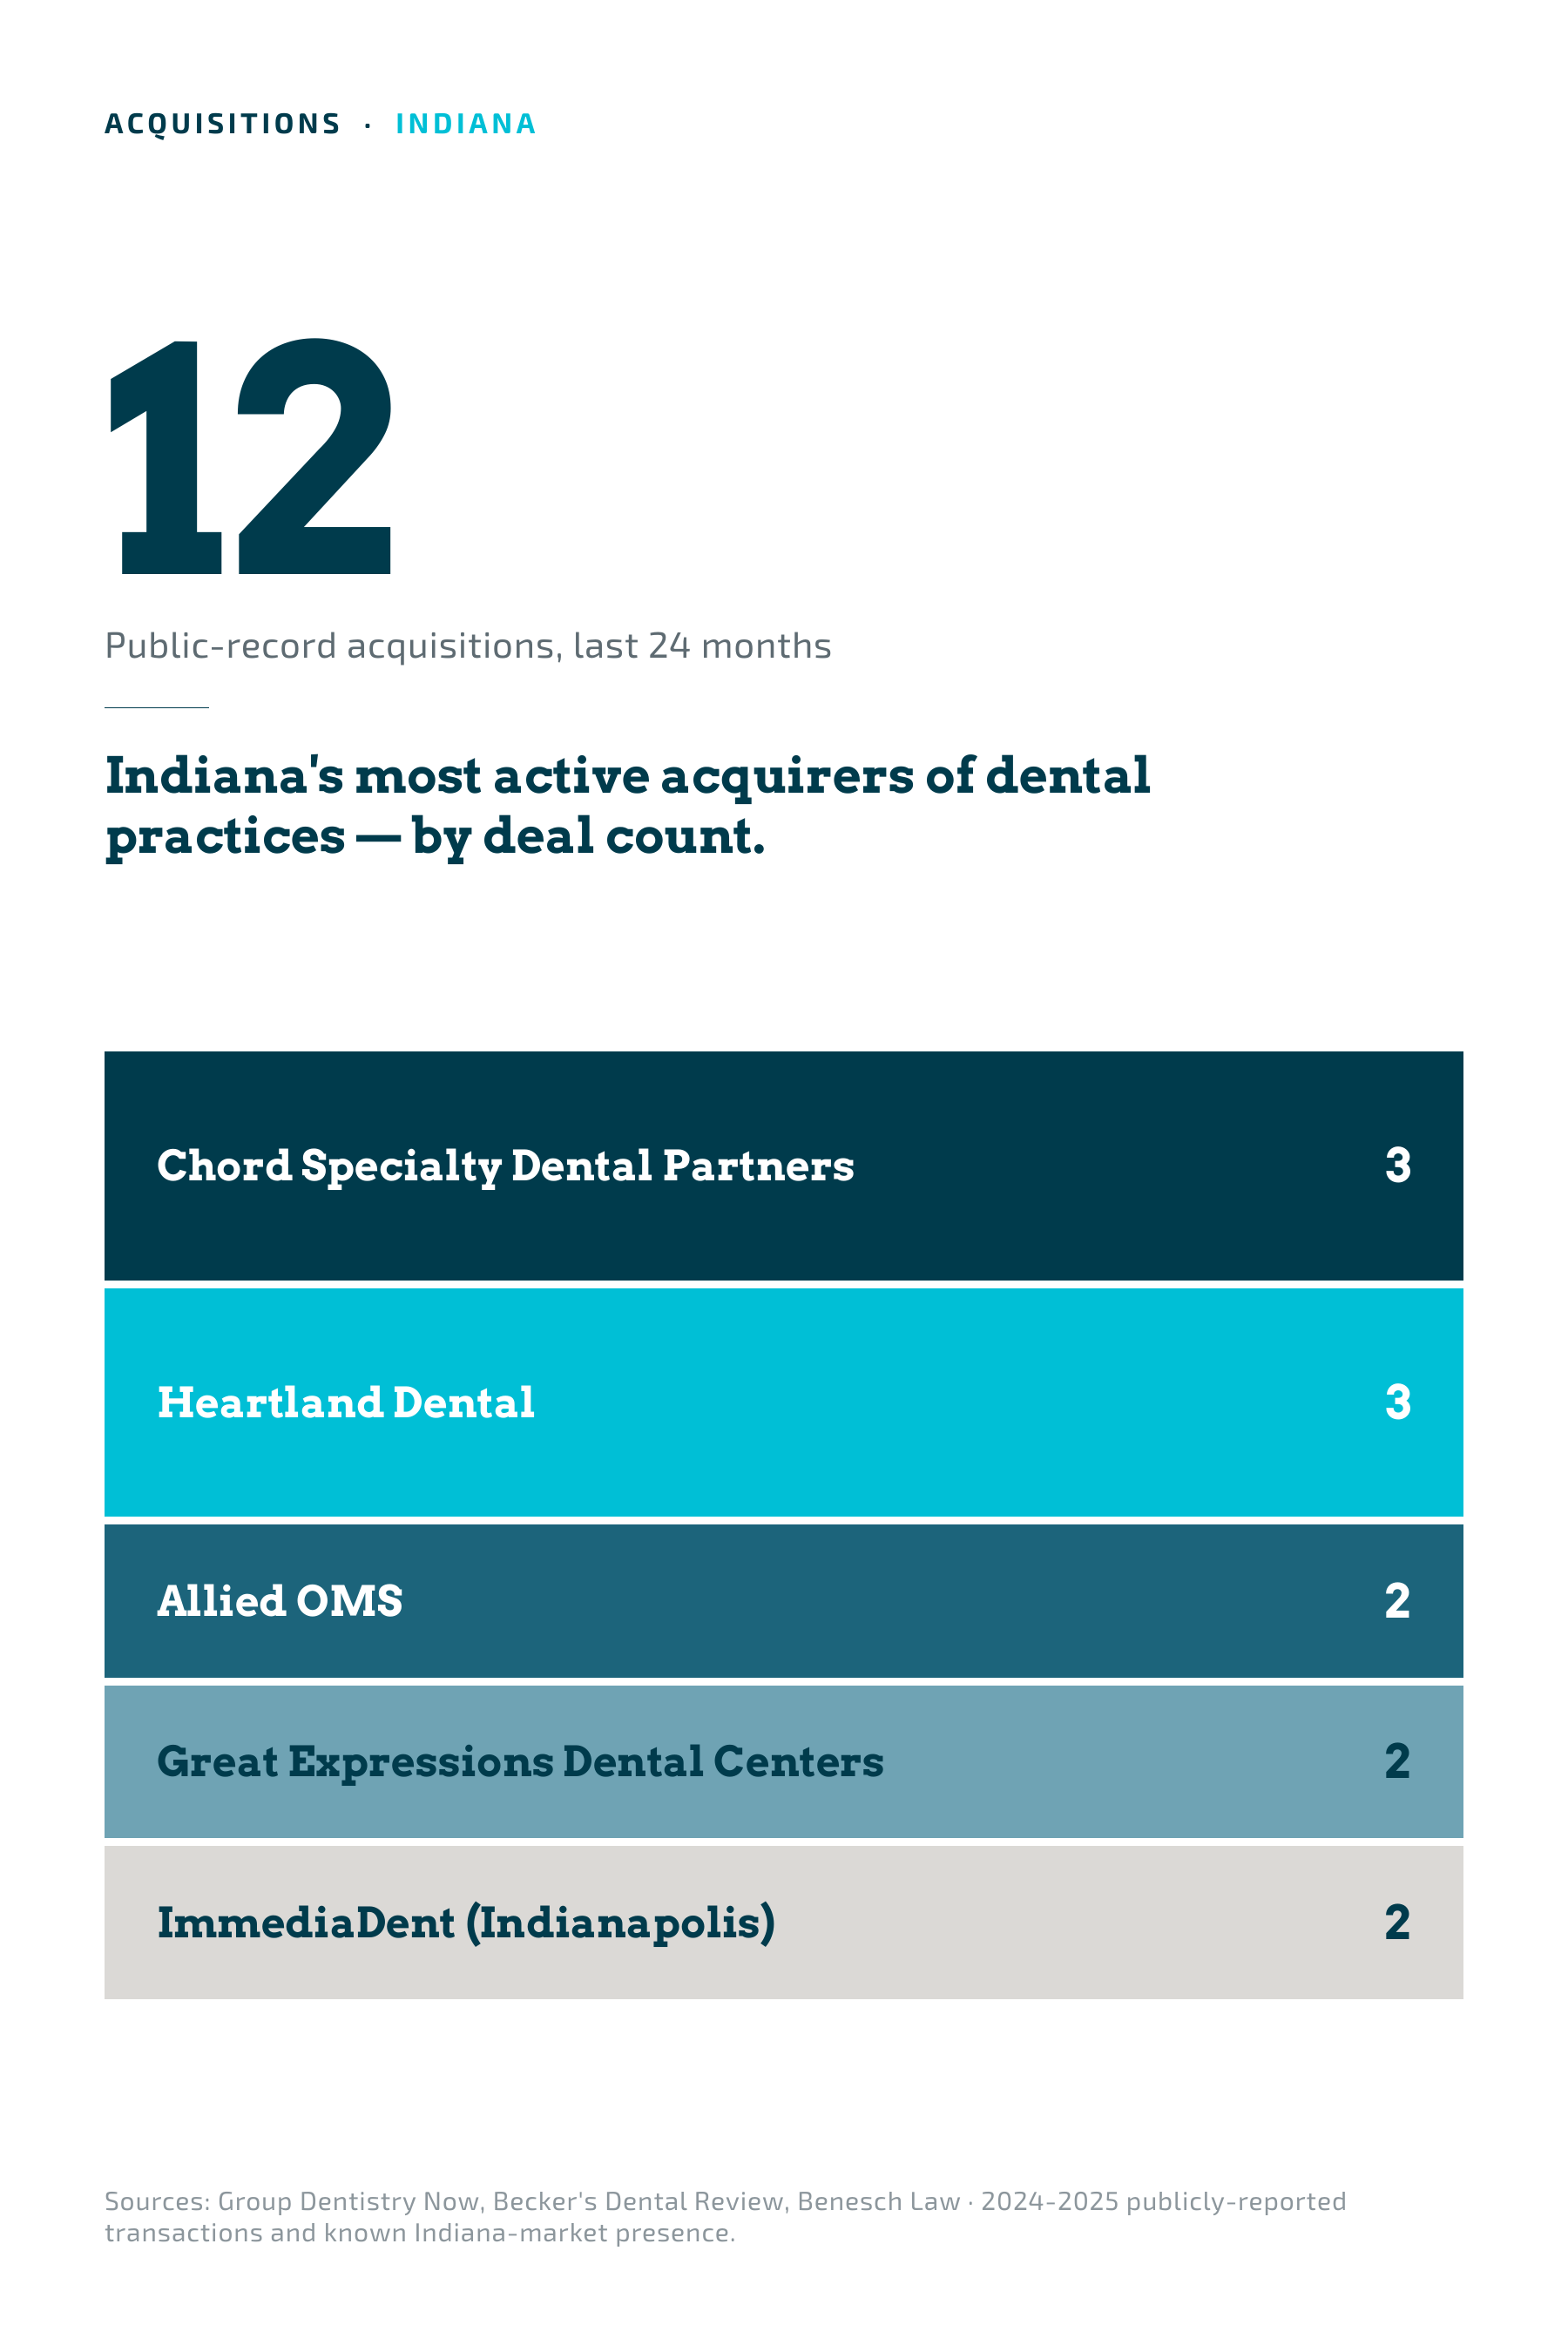
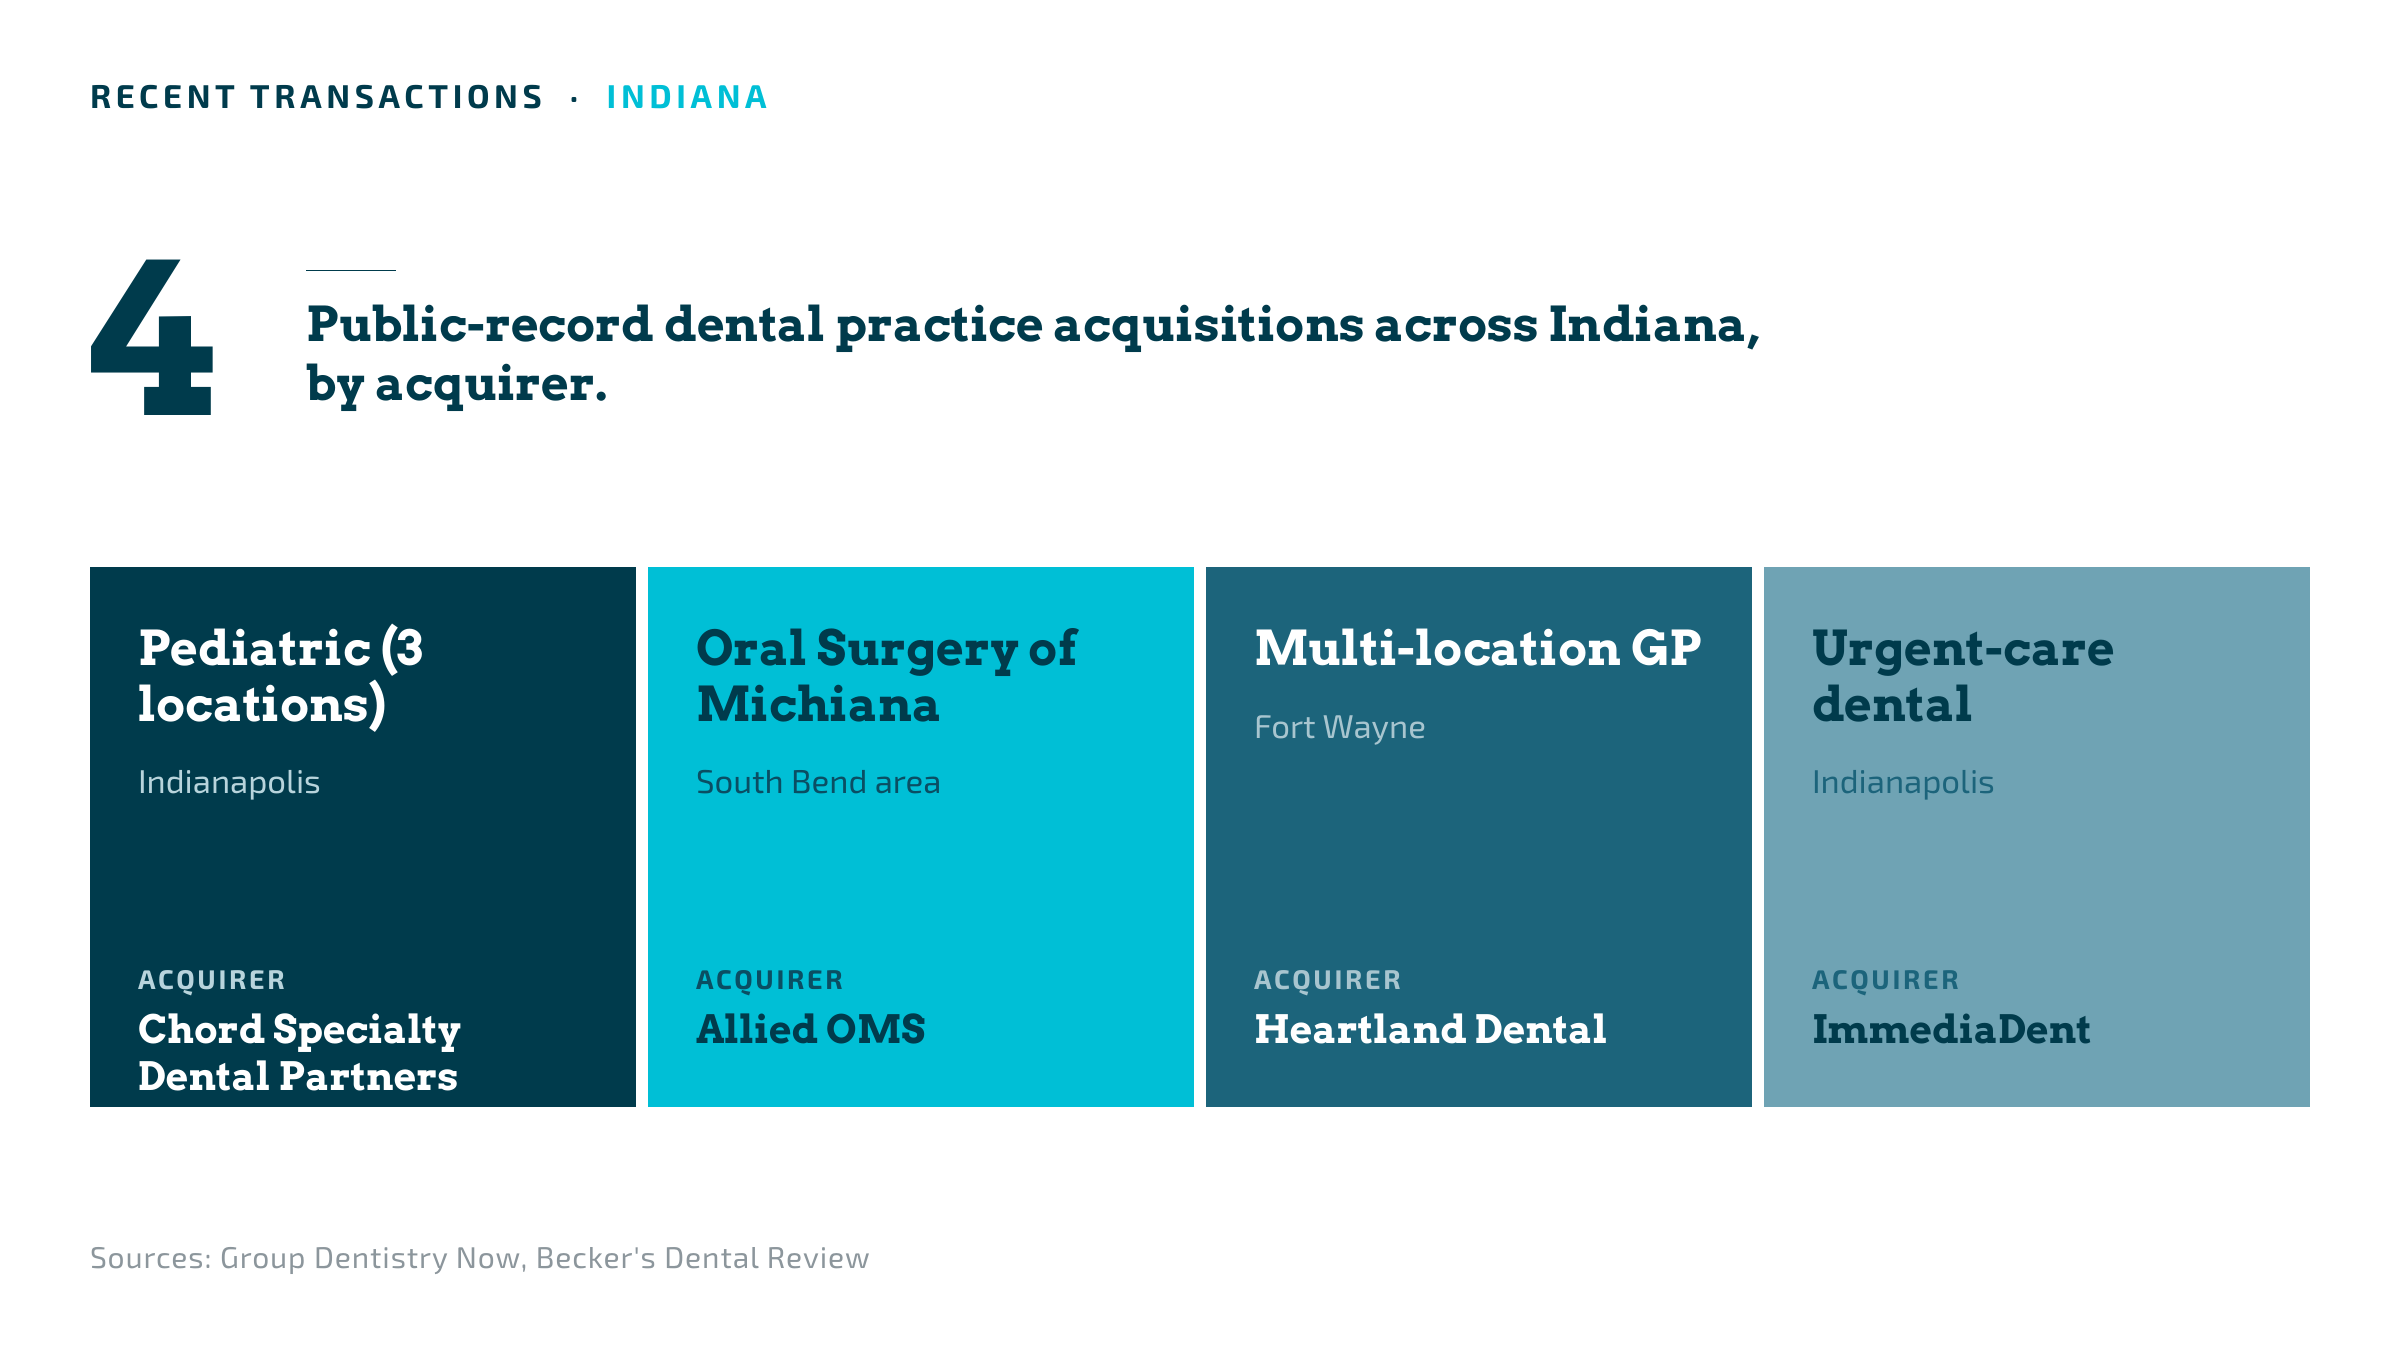
Indiana's DSO acquirer set skews Midwest-operational and specialty-focused: Chord Specialty Dental Partners' recent three-location Indianapolis pediatric expansion, Allied OMS's entry through Oral Surgery of Michiana, sustained Heartland Dental activity across Fort Wayne and Indianapolis, and Indiana-founded platforms like ImmediaDent. Different acquirers structure earn-outs differently, value operational stability differently, and honor MSO arrangements differently. That difference shows up at close. 

Indiana Rewards Operational Discipline. That Should Show Up in Your Valuation.

Solo Indiana practices currently transact at 3.5x–5.5x adjusted EBITDA. Multi-location groups with three or more locations clear 5x–8x. The spread inside those ranges is not about metro glamour — it is about margin structure, provider retention, patient concentration, and the cleanliness of your financial reporting. A properly prepared Indiana practice earns the top of the range. A rushed one doesn't. 

The Unsolicited Offer Is Calibrated to What You'll Accept.

Across TUSK's full sell-side practice, clients who arrived with an existing offer in hand closed, on average, 40% above that original number. In Indiana, the gap widens further when the offer's proposed MSO structure ignores HB 1666's new disclosure architecture — because those deals get re-priced later, and always in the buyer's favor. Structure your process before you respond to the offer. 

Stress-Test Your Offer
Most active acquirers of Indiana dental practices, by deal count

Proven Results for Indiana Practice Owners

average

6+
Competing Offers Generated

On average, TUSK generates 6 or more LOIs per transaction. In Indiana's active DSO market, that number frequently runs higher because more buyers means more leverage.

active

180+
Active Buyers in Our Network

Our buyer network includes 180+ DSOs, PE-backed groups, and strategic acquirers including the ones actively targeting Indiana dental practices today.

providers

40%
Average Increase Over Initial Offer

TUSK clients close, on average, 40% above the initial offer they would have accepted without representation. Your first offer is almost never your best offer.

Indiana Dentists. Real Numbers. Real Outcomes.

 These practice owners had the same questions you have right now. They received DSO offers. They wondered if the timing was right. They weren't sure who to trust. Here's what happened when they stopped navigating it alone. 

Dr. Philip Coniglio

5 stars

Owner of Suffolk Pediatric Dentistry & Orthodontics

“ Our practices have been at the forefront of dental care on Long Island for more than five decades. We trusted TUSK to identify the right DSO partner, one that aligned with our mission and helped us prepare thoughtfully for our next chapter. Their team went above and beyond to ensure we achieved both our financial objectives and the cultural fit that mattered most to us. We’re excited to partner with SALT Dental Partners and begin this new journey together. ”

Dr. James McDonnell

5 stars

Co-Founder of The Smile Lodge

“From day one, we wanted an advisor who would match the thoughtfulness and professionalism we brought to building The Smile Lodge. TUSK Practice Sales earned our trust quickly. Their pediatric experience in New York, data-driven valuation work, and steady guidance through diligence gave us confidence at every step.”

Mr. David Knopov

5 stars

Co-Founder of Gentle Dental World

“ The TUSK team was phenomenal throughout the entire process. Josh, Kevin, and Alex were there at every step of the process, ensuring we received the best deal for the great business our family has built in the Queens community. ”

How Indiana Dental Practice Sales Actually Get Done.

Selling a dental practice in Indiana isn't an event it's a process. The dentists who get the best outcomes are the ones who ran a structured, competitive go-to-market process with a sell-side advisor who works exclusively for them. Here's exactly what that looks like.

1

Discover

In a 30-minute strategy call, we map your financial picture, ownership structure, post-sale vision, and the specific outcome that would make this decision feel right. We need to understand what success looks like for you before a single buyer is ever contacted.

2

Educate

Most Indiana dentists who've received a DSO offer don't know what it's actually worth because the headline enterprise value and the realized value are often very different numbers. We walk you through how buyers construct offers, what each component means, and what a competitive outcome looks like in your specific market.

3

Analyze

Our team compiles your financial and operational data, calculates your adjusted EBITDA, normalizes your add-backs, and builds the narrative and documentation that commands serious attention from the right buyers. This work is what separates an 8x deal from a 5x deal.

4

Negotiate

We take your practice to market through a structured, confidential go-to-market process reaching qualified buyers in a coordinated sequence that creates competition, not just conversation. Buyers know they're competing against other buyers. That knowledge alone moves price.

5

Close

We don't step back at the LOI. TUSK defends your EBITDA through Quality of Earnings, translates every page of legal documentation, and ensures that what was promised in the term sheet is exactly what you receive at close. The deal isn't done until the money is in your account.

Confidentiality Isn't a Feature. In a Market This Interconnected, It's the Whole Job.

Indianapolis, Fort Wayne, Evansville, and South Bend — the four metros where most Indiana dental practice M&A concentrates — are close-knit professional communities. Study clubs, alumni networks from Indiana University School of Dentistry, referral relationships that go back thirty years. The patient who recognizes your name in a rumor, the associate who hears from a friend at another practice, the competing owner who reads a filing under the new HB 1666 rules — all of them affect your leverage the moment they know. 

Every buyer who receives a confidential information memorandum executes an NDA. We negotiate the specific components of the term sheet — MSO mechanics under Indiana's corporate-practice doctrine, earn-out language calibrated to Midwest patientretention patterns, the tax treatment that flows from Indiana's 4.9% corporate rate — before the headline number is finalized. We defend EBITDA through Quality of Earnings. The deal closes when the wire clears, not when the LOI is signed. 

Request a Confidential Valuation
Recent dental practice acquisitions in Indiana
user-client1.jpg

Client Success Story

“TUSK had been part of my journey from early on, they knew how much I poured into this business. I needed a partner who understood that selling wasn’t just transactional—it was deeply personal.”

Dr. Lori Noga

Tranquility Dental Wellness

Read More

Orthodontist Turns Practice Sale Into Generational Wealth at 40

It’s not uncommon for practice owners to call because life has changed, and they want their time, risk exposure, and future flexibility to reflect that reality.

A successful, second-generation orthodontist in the Midwest had built a two-location orthodontic practice with a strong reputation and real momentum. Financially, they were doing what disciplined owners do: consistently saving, steadily building wealth, and staying on track for long-term independence.

But three events converged in a short window that shifted the question from “Are we on pace?” to “Are we structured the right way for the life we want next?”

A local competitor had been acquired by an orthodontic service organization. The market clearly supported premium valuations for dental practices like theirs. And most importantly, a close family member had been diagnosed with a condition that brought a new level of urgency to being present, reducing stressors at home, and making sure the family had margin.

This wasn’t about walking away from orthodontics. It was about rebalancing life and risk while the market would reward it.

About The Practice:

  • Specialty: Orthodontics
  • Structure: 40 Year Old Single-doctor owner, two locations (Midwest)
  • Family Dynamics: Orthodontist was married with three children (13, 10, 8) Wife heavily involved in practice administration while also managing the home full-time
  • Starting point: No financial pressure to sell; consistent annual savings, household net worth ~$6.6M, but unclear how the practice’s worth impacted net worth.

This was a proactive decision to convert performance into protection, while the owner still had years of optionality ahead.

They knew their net worth, but not their options…

After the triggering events mentioned above, they turned to their trusted wealth advisor to understand their opportunities. The conversations led to more questions about:

  • How much of their household wealth was truly tied up in the practice?
  • If the market was favorable, what did “good timing” to sell their orthodontic practice actually mean in dollars and terms?
  • What would an orthodontic practice sale look like if the goal was to reduce clinical hours gradually, not abruptly?
  • How could they reduce the administrative load on the spouse without destabilizing operations?

Their wealth advisor introduced them to TUSK to run a valuation and pressure-test real exit paths. Once we ran the analysis and mapped the practice value against the household balance sheet and their personal goals, the decision-making became clear.

The valuation was the turning point.

It didn’t just produce a number. It translated the practice into a strategy on liquidity, risk reduction, and time.

What Success Looked Like In This Orthodontic Practice Sale

What they wanted was specific:

  • Take chips off the table and convert years of work into real liquidity
  • Reduce leverage and personal exposure so the family wasn’t carrying unnecessary risk
  • Create a path to step down clinically over time & reduce the administrative burden on the spouse
  • Protect culture, patient experience, and clinical autonomy across both locations
  • Select a partner aligned with how they wanted to operate, not just what they could pay

TUSK’s Approach: Create Leverage, Then Protect The Result

Our job as the orthodontist’s sell-side advisor was to find the right partner that would be able to achieve the financial and cultural elements the owner was looking for in the deal via our marketed sales process. The doctor was a young 40-year-old and was willing to stay for a minimum of 5 years, and knew they would be working alongside the buyer for that period of time. TUSK set out to canvas the market and bring multiple offers for our client to choose from.

We positioned the practice as a premium orthodontic asset with a clear growth and operational story, but we were equally direct about what mattered most to the owner: the right partner, the right structure, and the ability to protect the family’s time and stability.

Then we took it to market the right way, broad enough to create competitive tension, narrow enough to stay focused on fit.

Process Results:

  • 23 buyers brought to the table
  • 11 NDAs executed
  • 3 unique offers received from groups the owner was most excited to partner with

“TUSK introduced us to DSOs we didn’t even know existed.” 

The Decision: They Didn’t Choose The Highest Offer

Once the doctor had three real offers from respected groups, the decision became more nuanced because the “best deal” is rarely defined by headline value alone.

This owner chose the partner that aligned with their team, their culture, and their long-term autonomy, not the offer with the highest enterprise value. And because we had created legitimate leverage in the process, they had the freedom to make that choice without sacrificing outcomes elsewhere. An important feature of their deal was the group was nearing a recapitalization event compared to the other groups, allowing them to monetize on their equity sooner.

Fit mattered because this wasn’t an exit. It was a transition.

The winning partner was the one who could operationalize the owner’s gradual step-back, reduce friction for the spouse, and protect the practice’s culture across both locations.

The Outcome: Reduced Risk, More Flexibility, & Meaningful Time Back

The outcome was exactly what they came to the table for, just executed earlier in their lifespan than they originally thought possible.

They reduced leverage and personal risk while the market was favorable. They increased financial security at age 40, which created real flexibility around how aggressively they needed to work. And the day-to-day burden on the spouse eased, because the practice no longer required the same level of administrative weight from within the household.

The owner signed a five-year employment agreement with a clear plan to gradually reduce clinical hours over time, maintaining continuity for patients and staff while moving toward the family-first structure they wanted.

Why This Worked And What Doctors Can Learn From It

This is what we see repeatedly in premium transitions:

  • The strongest deals often happen when the owner is informed and prepared
  • Clarity on goals drives better structure and better partner selection
  • A controlled marketed sales process creates leverage, and leverage protects terms
  • The “right” buyer is the group that can support the owner’s future, not just purchase the past

The Takeaway
If you want to reduce risk and reclaim time while you’re still young enough to enjoy it, the first step isn’t deciding to sell. It’s understanding what your practice is worth and what options that value creates.

For owners weighing a similar decision

If you’ve experienced a life event that changes your priorities or you simply want to reduce risk while the market is strong, you don’t have to start with a binary decision.

Start with clarity.

A valuation, paired with a real conversation about goals and structure, will tell you what’s possible and what a smart transition could look like without sacrificing autonomy or culture.
What Indiana Dentists Need to Know Before They Sell.

The Indiana DSO market moves fast. These resources give you the market intelligence buyers don't want you to have - so you walk into every conversation prepared.

Frequently Asked Questions - Selling a Dental Practice in Indiana

Active and mid-tier. Indiana has 3,265 active dentists (ADA HPI 2023), with 92% in general dental practice per the Indiana Dental Association's 2024 workforce survey. Public-record M&A activity over the trailing 24 months includes Chord Specialty Dental Partners' three-location Indianapolis pediatric acquisition, Allied OMS's entry through Oral Surgery of Michiana in the South Bend area, and ongoing Heartland Dental expansion across Fort Wayne and Indianapolis. 69% of DSO private-equity sponsors expect moderate-to-high 2026 acquisition activity, and Indiana's operational stability makes it a target for buyers seeking durable EBITDA rather than growth corridor upside. 

Direct outbound offers are sized to what a single seller is likely to accept, not to what a competitive process would clear. Across TUSK's sell-side practice, clients who arrived with an unsolicited offer in hand closed, on average, 40% above that initial number. In Indiana specifically, the MSO structure the acquirer proposes on day one — and how it maps to the new HB 1666 reporting architecture that took effect July 1, 2025 — materially affects your tax outcome, your clinical autonomy, and your disclosure exposure years out. The advisor's job is to make sure the structure beneath the number holds up. 

A properly-run Indiana process typically runs six to nine months. As a working benchmark: four to eight weeks of financial preparation and positioning, four to six weeks of buyer outreach and NDA execution, four to six weeks of offer negotiation, and 60 to 90 days for due diligence and legal close. Indiana deals frequently add two to three weeks at legal close to structure the MSO arrangement properly under HB 1666's revised reporting framework. The buyers who try to compress that timeline are usually the ones whose structure won't hold up on later scrutiny. 

 Adjusted EBITDA times a market multiple — but Indiana specific factors shape where in the range your practice clears. Solo owner-operator practices currently transact at 3.5x–5.5x adjusted EBITDA in Indiana; multi-location groups with three or more locations command 5x–8x. Where you land depends on margin structure, provider retention, patient concentration, and the cleanliness of your financial reporting. Indiana's 2.95% flat personal income tax and 4.9% corporate rate — one of the lowest in the Midwest — also affect the after-tax math on cash-at close versus rollover equity. The only way to know your number in today's market is a formal valuation, which TUSK provides at no cost. 

 It is not. Indiana's M&A window favors sellers right now: buyer demand is stable, supply is constrained by the demographics of an aging owner base, and the July 2025 HB 1666 reporting-law change is still settling. Owners who engage TUSK 12 to 24 months ahead of going to market typically use the time to clean up financial reporting, address provider concentration, normalize compensation, and pre-position the MSO structure to comply cleanly with the new rules. That preparation has produced valuation increases of 30%+ before a single buyer is contacted. A valuation conversation is not a commitment to sell. It is the information you need to decide on timing. 

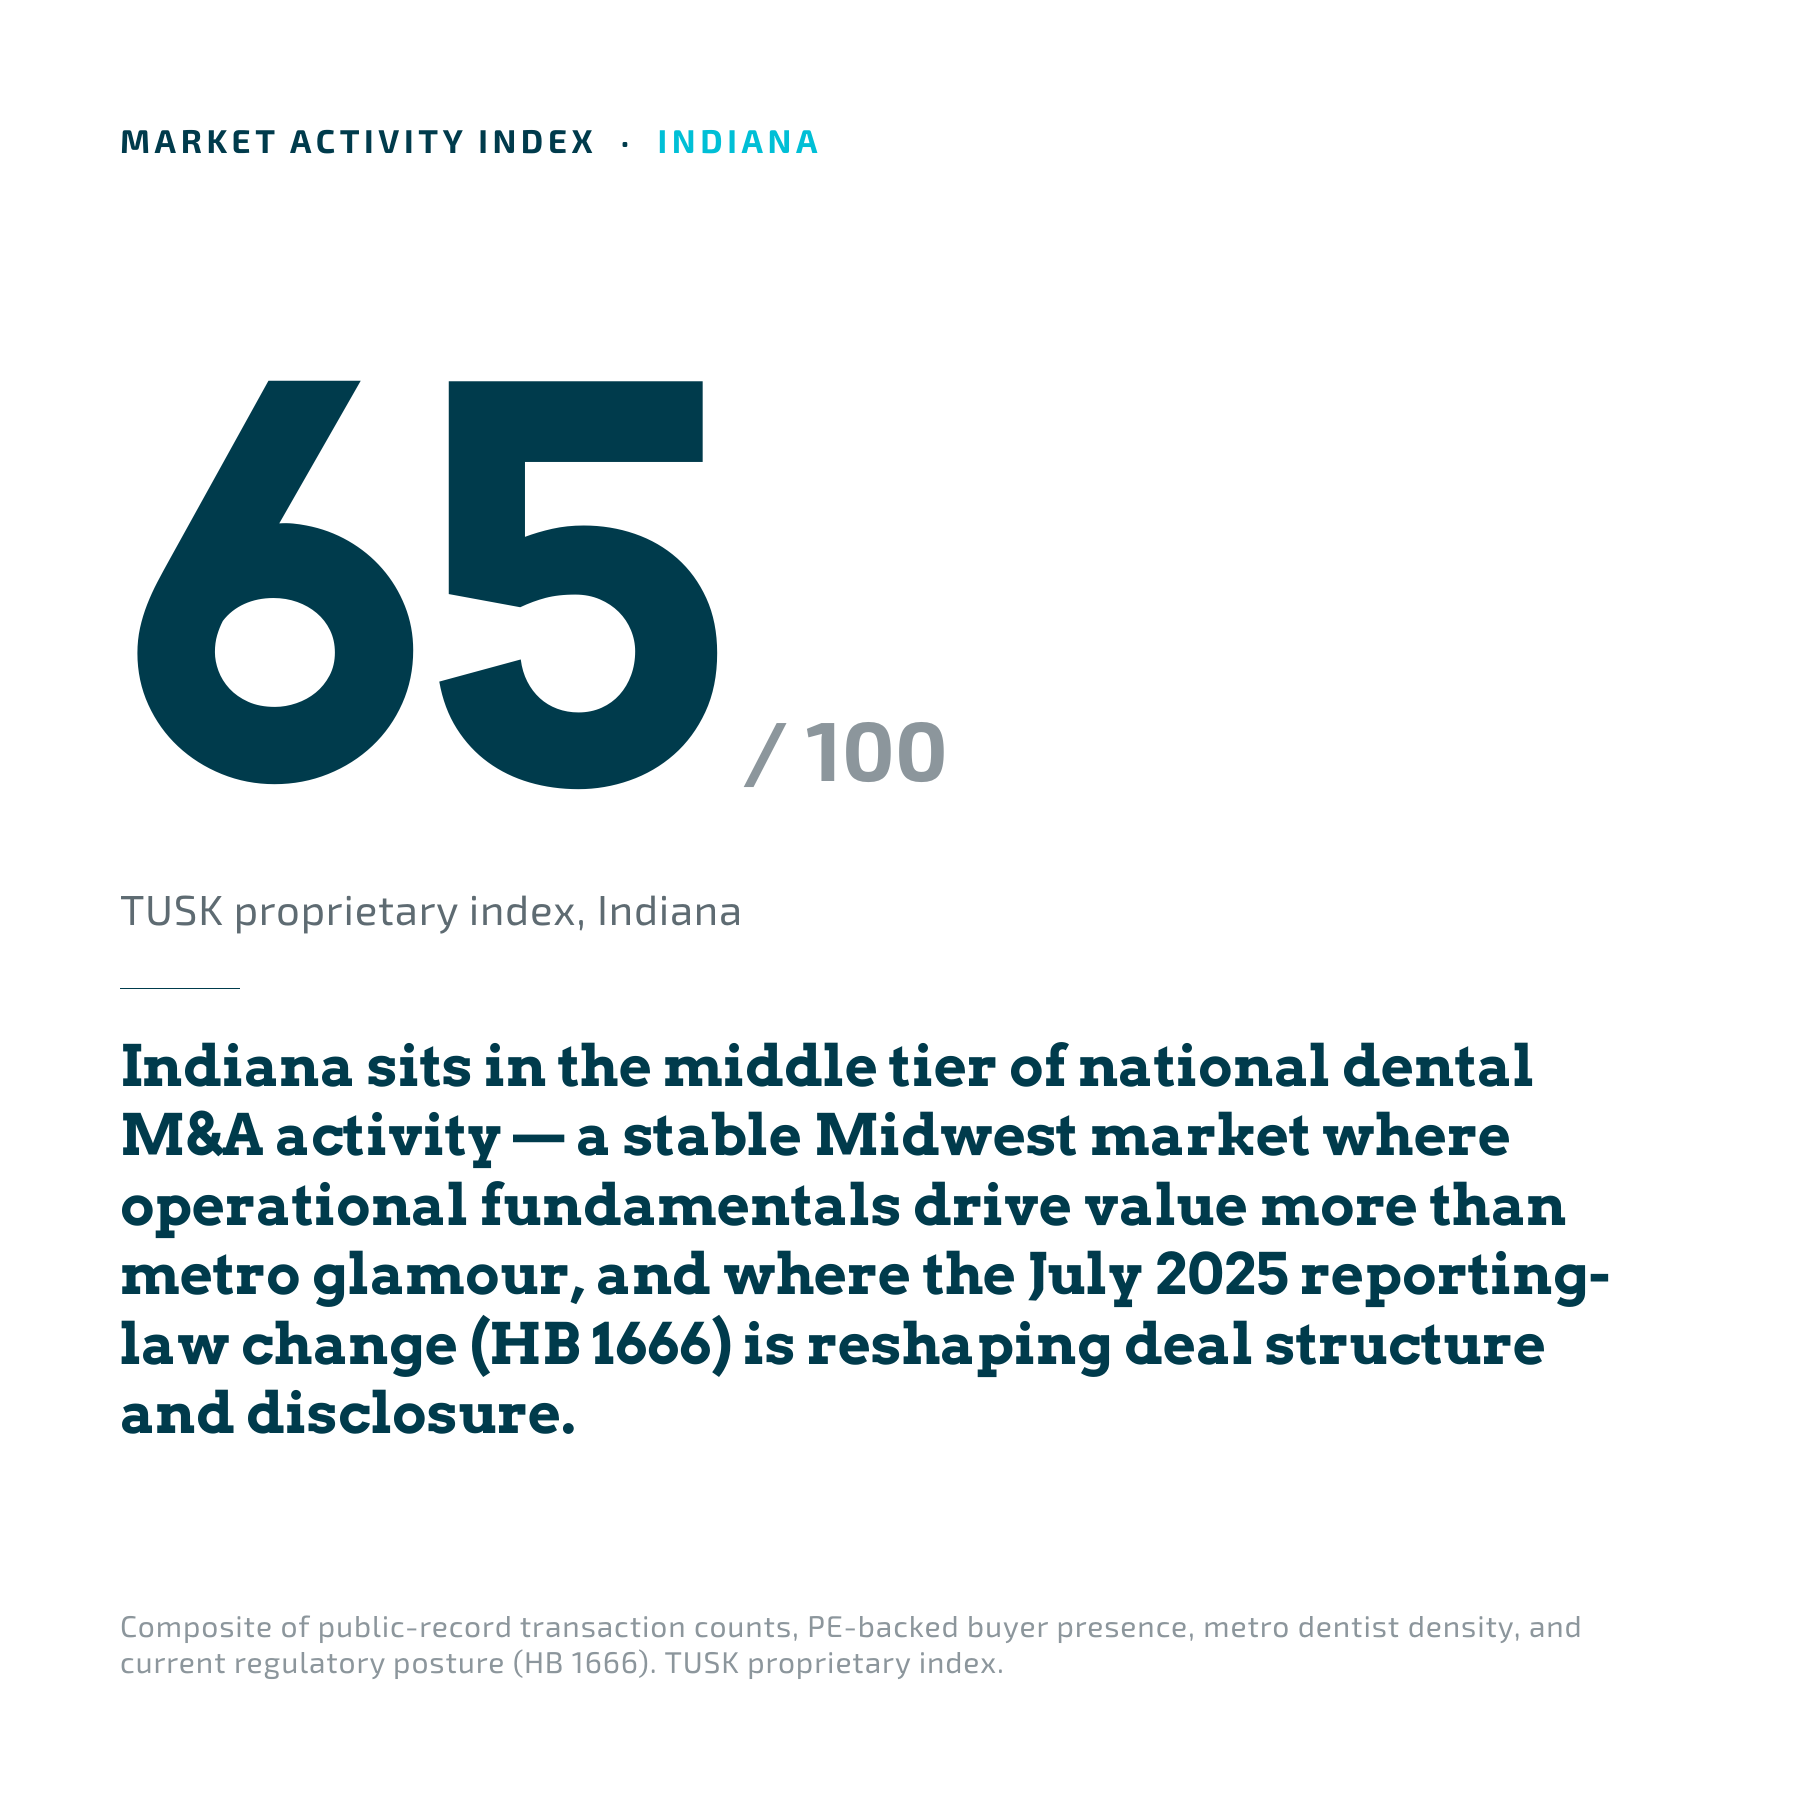
Indiana dental practice market activity index

Indiana Owners Have Leverage Right Now. Start With a Valuation.

Sixty-nine percent of DSO private-equity sponsors expect 2026 acquisition activity to increase. The Indiana practices closing in Indianapolis, Fort Wayne, Evansville, and South Bend are doing so with multiple competing offers, structured to comply cleanly with HB 1666's new reporting requirements, and represented by sell-side counsel who understands how Midwest deals actually clear. A confidential valuation is where every successful Indiana dental practice sale begins. No commitment. 

Contact Us

Request a Confidential Valuation

Prepared by TUSK's team. We respond within two business days.